The world's first real-time structural intelligence engine. The London Market, read in full.
The engine, the Architectural Formula, applied across the entire London specialty market. Every assessed carrier scored, classified, ranked on a live continuum. Not a survey. Not analyst commentary. The structural consequence arrives in the financial results before most carriers see it coming.
Download the Assessment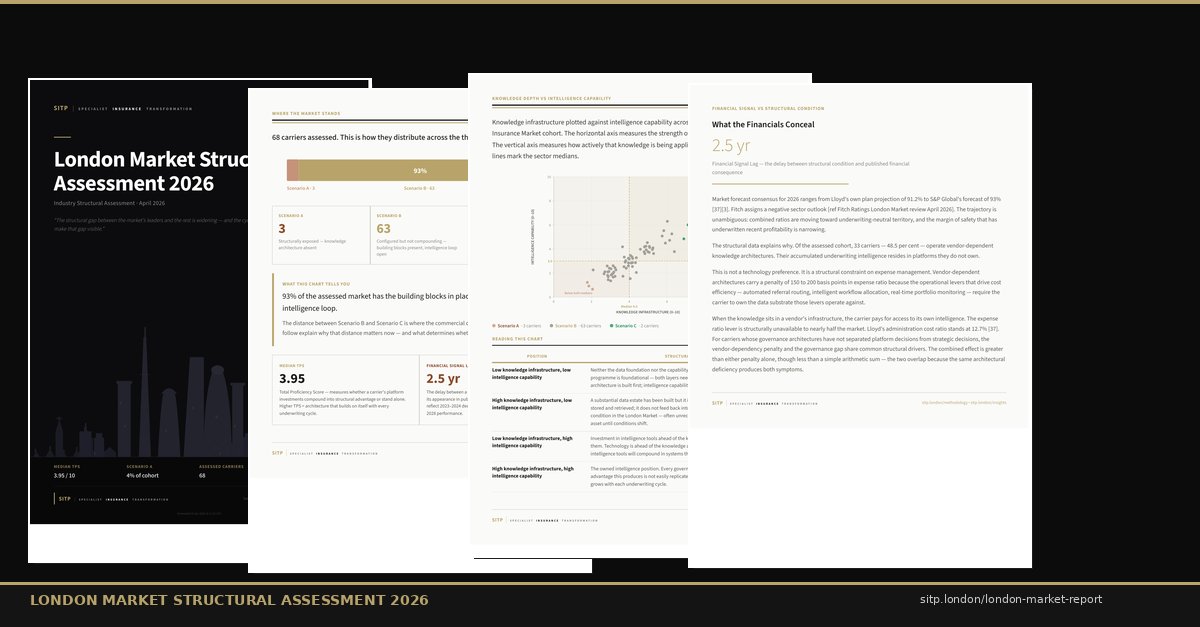
Download the London Market Structural Assessment 2026.
The complete structural read on the London Market, cohort classification, dimensional scoring, aggregate financial consequence, five-force implications, and falsifiable predictions tracked against evidence. Business email required.
The structural gap has a financial consequence.
The London Market, assessed against four structural scenarios, read 8 October 2026. A scenario with no member in the cohort at this read is not shown.
The median filed combined ratio for 2024 across the cohort's filers is 86.9%. 21 members sit above that median, by an average of 6.0 combined-ratio points. Source class: audited filings, every input cited to its filing.
21 of 170 scored members of the London Market cohort (60 with a like-period 2024 filing, groups counted once), read 8 October 2026
Engine classification context, the latest reading per carrier (the engine's own classification): 26 confirmed, 150 ambiguous, 257 latent, of 433 carriers carrying a classification.
The practice's position is that structural remediation addresses this drag.
The members above the median, each cited to its filing
| Member | Filed combined ratio | Drag | Filing |
|---|---|---|---|
| Fidelis Insurance | 121.9% | +35.0 pts | Lloyd's Syndicate Annual Accounts, Syndicate 3123, regulatory |
| QBE European Operations | 102.9% | +16.0 pts | Lloyd's Syndicate Annual Accounts, Syndicate 2999, regulatory |
| Atrium Underwriters | 99.5% | +12.6 pts | Lloyd's Syndicate 609, FY2024, regulatory |
| Arch Insurance | 98.9% | +12.0 pts | Lloyd's Syndicate Annual Accounts, Syndicate 2012, regulatory |
| Dale Underwriting Partners | 97.8% | +10.9 pts | Lloyd's Syndicate 1729, FY2024, regulatory |
| CNA Hardy | 96.8% | +9.9 pts | CNA Financial FY2024, Hardy segment, regulatory |
| Blenheim Underwriting | 91.6% | +4.7 pts | Lloyd's Syndicate Annual Accounts, Syndicate 0382, regulatory |
| Brit Insurance | 91.1% | +4.2 pts | Brit Group Holdings FY2025 Annual Report (discounted CR), regulatory |
| RenaissanceRe | 90.3% | +3.4 pts | Lloyd's Syndicate Annual Accounts, Syndicate 1458, regulatory |
| Somers Syndicate Management | 90.3% | +3.4 pts | Lloyd's Syndicate Annual Accounts, Syndicate 0218, regulatory |
| Ki Insurance | 90.0% | +3.1 pts | Lloyd's Ki Syndicate, FY2024, regulatory |
| Starr Companies | 89.0% | +2.1 pts | Starr Companies FY2024, public |
| MS Amlin | 88.9% | +2.0 pts | Lloyd's Syndicate Annual Accounts, Syndicate 2001, regulatory |
| Lancashire | 88.6% | +1.7 pts | Lloyd's Syndicate Annual Accounts, Syndicate 3010, regulatory |
| Tokio Marine HCC | 88.5% | +1.6 pts | Tokio Marine HCC FY2024, public |
| Westfield Specialty | 88.0% | +1.1 pts | Lloyd's Syndicate 1200, FY2024, public |
| Apollo 1969 | 88.0% | +1.1 pts | Lloyd's Syndicate Annual Accounts, Syndicate 1971, regulatory |
| Axis Syndicate 1686 | 87.8% | +0.9 pts | Lloyd's Syndicate Annual Accounts, Syndicate 1686, regulatory |
| Swiss Re | 87.7% | +0.8 pts | Swiss Re FY2024 Annual Report, public |
| Inigo/Radian | 87.2% | +0.3 pts | Lloyd's Syndicate 1301, FY2024, regulatory |
| MUNICH RE SYNDICATE LIMITED | 87.1% | +0.2 pts | Lloyd's Syndicate Annual Accounts, Syndicate 0457, regulatory |
Read structurally, the London Market is not one market. The split is near binary: a carrier whose intelligence loop is not yet closed surrenders the return on what it learns, and a carrier whose architecture compounds keeps it.
The asymmetry is sharp enough to price. It will materialise through the cycle, whether through cost of capital, acquisition economics, or the quiet erosion of broker mindshare, in the eighteen to thirty-six months ahead.
The aggregate is the market view. There is also a carrier view.
Your carrier. Your role. Structural intelligence narrated.
The Architectural Formula, applied to your carrier specifically. Dimensional scores, scenario classification, binding constraint, cohort rank. Narrated for your role, CEO, CUO, CFO, CTO, CRO, COO, CDO, CIO, or Board. Same engine. Same methodology. Your carrier as the subject.
Two products. One instrument.
Four attributes. One intelligence product.
Structural Intelligence is a category. These are the properties that separate it from market research, analyst commentary, and conventional consulting deliverables.
From filing to briefing in hours.
Regulatory, financial, and commercial signals flow through the pipeline continuously. Your structural reading reflects today's market, not last quarter's. Not next quarter's report.
One framework, applied identically.
Every carrier scored on the same axes. No favoured client. No analyst subjectivity. Cohort benchmarks are real because the methodology is held constant across the entire assessed universe.
Scores, classifies, predicts.
Scenario classification, dimensional profile, peer rank, binding constraint. Falsifiable predictions tracked against real evidence, not narrative commentary dressed as insight.
No vendor affiliations.
Zero vendor alliances. Zero referral fees. The only structural intelligence in the London Market unclouded by the commercial interests of platform vendors, integrators, or analyst sponsors.
The London Market Structural Assessment 2026 is produced using A Universal Theory of Business Strategy, a proprietary analytical framework validated across 1,003 businesses over six decades, consolidating 18 canonical strategic frameworks and accounting for 281 empirical cases with zero exceptions to its predictive structure.
The framework, its constituent formula, dimensional weightings, and scenario thresholds are the unpublished intellectual property of SITP. They are protected as unregistered design right and trade secret under the Copyright, Designs and Patents Act 1988 and are not disclosed in published output. Carriers receive the conclusions, evidence, and predictions; the calculation surface remains proprietary.